What a roof damage report for insurance claim review needs to show
A roof damage report for insurance claim purposes is a dated record of what happened to a specific roof and what condition it is in now. Your carrier will decide the claim on what you can show, not on what you remember. Four things carry most of the weight.
Damage described in numbers
Write down counts and measurements, not impressions. “Twelve cracked and five missing shingles on the north slope” tells an adjuster something. “Shingles are damaged” does not. Measure the dents in flashing and gutters. Measure the water stain on the ceiling. Note the slope and elevation where each item sits.
The weather event, dated and sourced
Your policy responds to a covered event, so connect the damage to one. Record the date and time. Pull the reported wind speed or hail size from a public weather record for your area and keep a copy. Then read your own policy for the deductible and for any separate wind or hail provision, because those clauses change the arithmetic more than most owners expect.
Photographs that establish location and scale
Shoot wide before you shoot close. A wide frame shows which elevation you are looking at. A close frame shows the defect. Put a coin or a tape measure next to hail bruising so the size is not a matter of opinion. Turn on the date stamp. Photograph the interior evidence too, because a ceiling stain under a damaged slope links the two together.
A timeline of everything you did
Log the date you discovered the damage, the date you tarped anything, every call to the carrier with the name of the person you spoke to, and every contractor visit. Keep receipts for temporary repairs. Most policies require you to prevent further damage, and those costs are often recoverable.
How to document damage without getting hurt
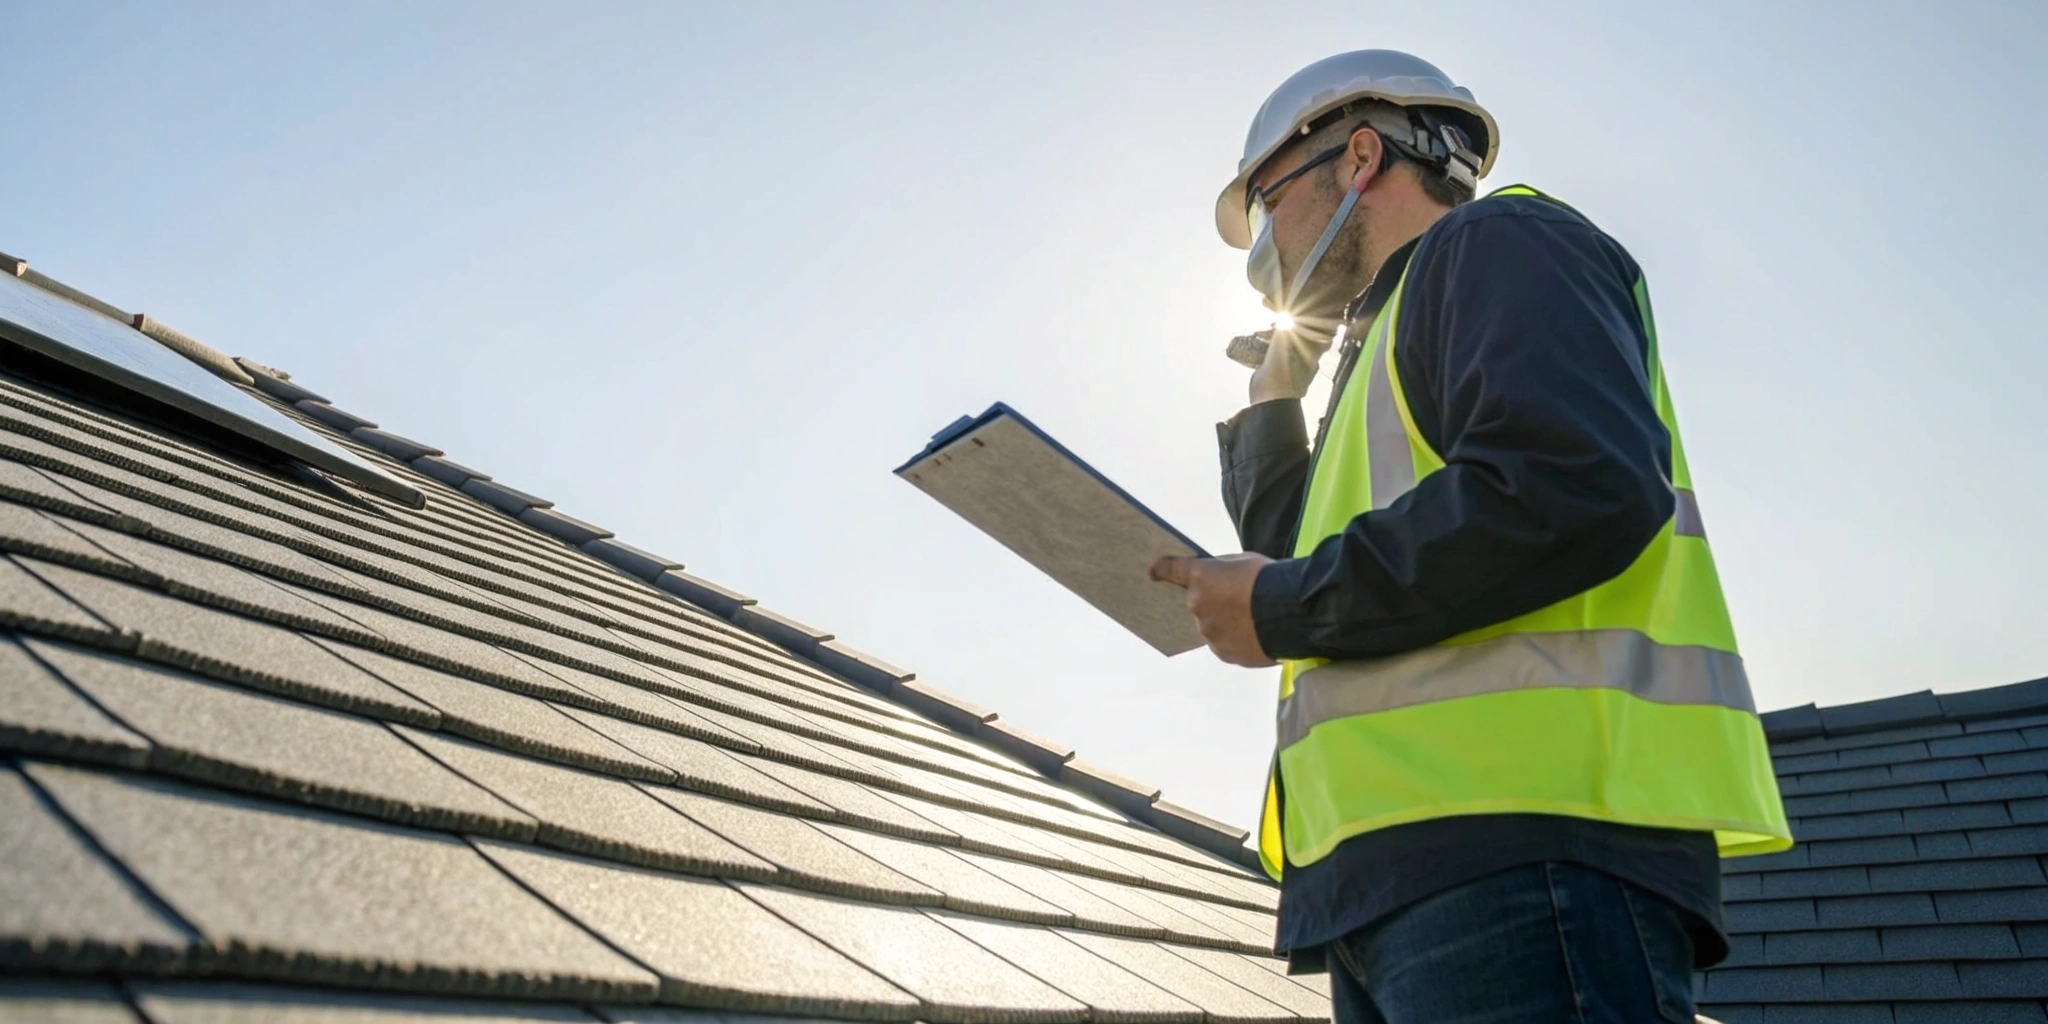
Stay off a roof you think is damaged. Decking can be soft in places that look fine from the edge, and no photograph is worth a fall.
Start inside instead. In the attic, look for damp insulation, dark staining on the sheathing, daylight at penetrations, and active drips. In the rooms below, look for spots, discoloration and peeling paint. Then walk the perimeter from the ground. Check gutters and downspouts for shingle granules, look for lifted or bruised shingles with binoculars, and check flashing at chimneys, vents and skylights. Anything above that belongs to someone with fall protection and training.
Four things that weaken a claim
- Thin documentation. Gaps in the record become the carrier’s argument about scope and cause. Take more photographs than feel necessary.
- Waiting. Policies set reporting windows, and a delay makes it harder to tie the damage to one storm. Secondary damage that develops while you wait may fall outside coverage.
- Skipping a professional inspection. Hail bruising, wind-lifted tabs and failed seals are hard to see from the ground and easy to miss from a ladder. They are also the findings that decide claims.
- Going quiet with the adjuster. Be present for the site visit. Walk the property, point to what you documented, and ask questions while everyone is standing there.
When to bring in an accredited inspector
The adjuster who visits your property works for the carrier. That is their job, and a good adjuster does it fairly. An independent inspection gives you a second set of documented findings prepared to a published methodology, which is a different thing from a repair estimate.
NRCIA members inspect roofs to the LeakFREE® Check, a five-zone method covering interior, attic, exterior, perimeter and rooftop. The member produces a LeakFREE® Roof Inspection Report that identifies what was observed in each zone, with photographs tied to each finding. NRCIA sets that standard and accredits the members who work to it. The association does not inspect roofs or write reports itself.
Members holding the DisasterGUARD™ accreditation carry additional training in insurance-related evaluations, which matters when a claim turns on separating storm damage from age and wear.
Certification after the repairs are done
Once the work is complete, an accredited member can inspect the roof again and, if it meets the published criteria, issue a LeakFREE® Roof Certification through InspectionPLUS®. The certification records that this roof, at this address, on this date, met those criteria. Its term is set by the findings, the slope, the materials and the condition, up to a maximum of ten years, and the expiration date is printed as a date.
Be clear about what it is. A certification is a record of condition. It is not insurance, not a service contract, and not a promise that the roof will never leak. Re-inspection is triggered when repairs are performed by anyone other than an NRCIA member.
LeakFREE® is our federally registered trademark. Only NRCIA members can issue a LeakFREE® certification.
Presenting the file
Organize the report the way an adjuster reads: a cover page with your name, address and policy number, then sections by location. “North Slope,” “Interior Ceiling Damage,” “Gutters and Flashing.” Under each heading, put the written description, then the photographs that support it, named so the file name says what the picture shows. Add the timeline and the receipts at the back.
If the settlement offer does not cover the documented scope, say so in writing and ask for the reasoning in writing. Point to specific findings and specific estimates. If the file is complete, the conversation stays about the roof.
Find an accredited NRCIA inspector near you in the member directory.
LeakFREE®, Forensic ROOF®, Mr. RoofCheck®, InspectionPLUS®, Today’s Inspection… Tomorrow’s Protection®, and Got Leaks?® are registered trademarks of Field Gate FLP, used by permission. RoofGUARD™, ForensicGUARD™, DisasterGUARD™, E3GUARD™, and Think Like a Raindrop™ are trademarks of Field Gate FLP.