Before you file: is this a claim worth making?
The roof claim process starts before you dial the carrier. Two questions decide whether filing helps you. Does the damage plausibly exceed your deductible, and can you tie it to a sudden event the policy covers? A handful of missing shingles on a fifteen year old roof may cost less to fix than the deductible, and a filed claim stays on your record either way.
Start from the ground with binoculars. Look for lifted, cracked or missing shingles, dents on gutters, downspouts and vents, and a heavy load of granules where the downspout empties. Then go inside with a flashlight. Damp insulation, dark rings on the roof deck, daylight through the sheathing, yellow-brown stains on a ceiling, paint that bubbles near the ceiling line. Any of those is worth photographing today.
Stay off the roof. A ladder in the days after a storm is how a property loss becomes an injury.
Document the damage before you call
Your file is the strongest thing you bring to the roof claim process, and it is easiest to build in the hours right after you notice the damage.
Photos and video
Shoot wide, then close. Wide frames establish where the damage sits on the roof and how much of it there is. Close frames show the character of it: a hail bruise, a torn tab, a lifted ridge cap, split sealant at a vent boot. Photograph interior damage too, because the ceiling stain is part of the same loss. Video helps most where water is actively moving.
A written log
Open a notebook or a single document and date every entry. Record when you noticed the damage and what weather preceded it. Log every call: date, time, the name of the person, what was said, what they promised. Keep receipts for tarps, plywood and anything else you buy to stop further damage. Carriers generally expect you to mitigate, and those costs are frequently reimbursed.
An independent inspection report
A report from an accredited inspector who is not selling you the repair carries a different weight than a contractor’s estimate. It describes what failed, where, and what the observed cause appears to be, with photographs attached. A LeakFREE® Roof Inspection Report follows a multi-zone process covering the interior, attic, exterior, perimeter and rooftop, so the findings arrive in a consistent order rather than as a list of whatever caught someone’s eye.
The roof claim process, step by step
- Call the claims line. Have the policy number ready and describe the damage and the date it happened. Write down the claim number and the adjuster’s name and contact details.
- Check your deadlines. Policies set a window for reporting, and some are short. Read the notice provision rather than guessing.
- Confirm ACV or RCV. Actual Cash Value pays the depreciated value of the roof. Replacement Cost Value pays what it costs to replace it today, less your deductible. This single line changes the settlement more than anything else in the file.
- Send your documentation. Photos, the log, receipts and the inspection report, in one organized package with the claim number on it.
- Schedule the adjuster visit. Pick a time you can actually attend.
The adjuster’s inspection
This is the pivot point of the roof claim process. The adjuster is there to decide whether the damage came from a covered event and what it costs to put right. They take their own photographs and write their own report, and that report drives the offer.
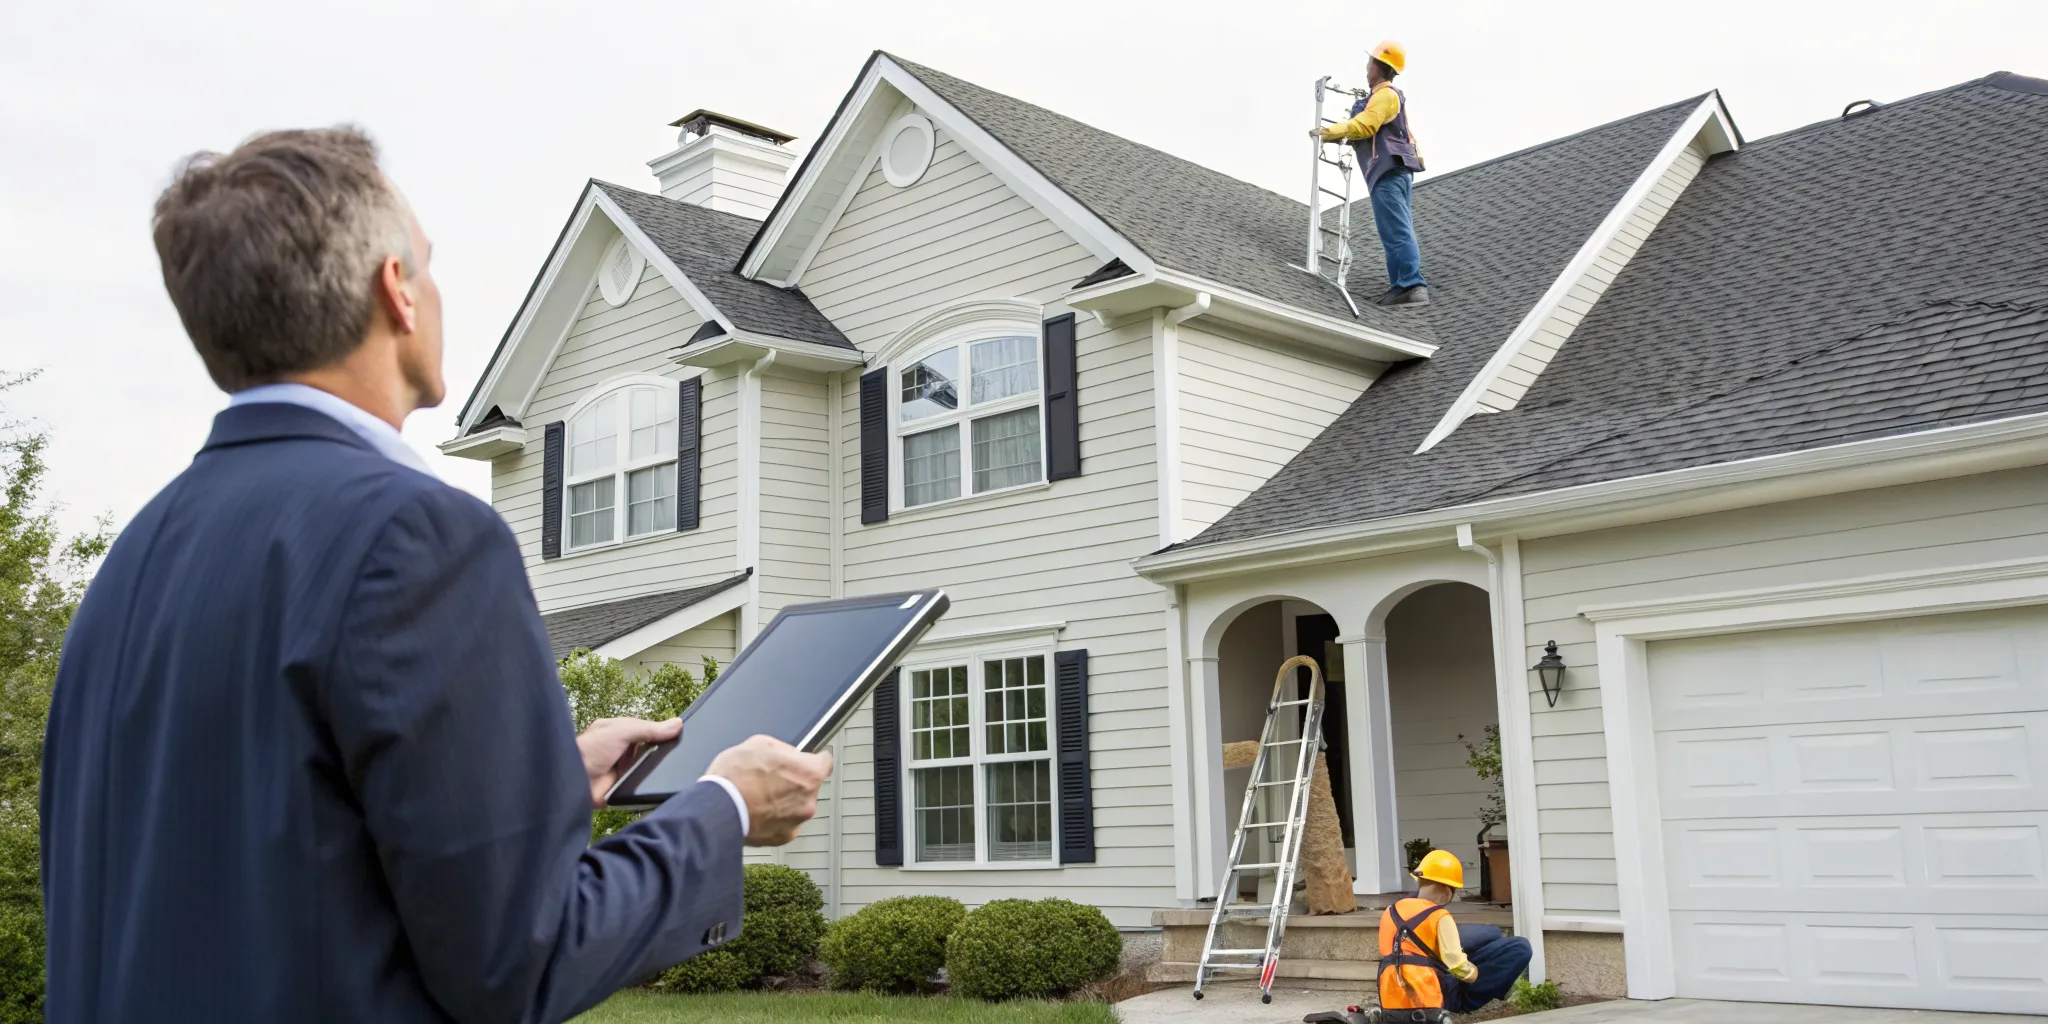
Be present. Walk them to each area you documented and hand over your photographs. Ask your roofing contractor to attend as well, so the technical conversation happens between two people who read roofs for a living. A contractor can point at a soft spot in a deck or a bruised mat that reads as nothing from twenty feet away.
If the adjuster recommends a temporary repair such as tarping, do it and keep the receipt.
How the settlement is calculated
Three inputs set the number: your policy language, your deductible, and the age and condition of the roof at the moment of loss. On an RCV policy the money usually arrives in two payments. The initial check covers actual cash value minus the deductible, which funds materials and a permit. After the work is finished and invoiced, the carrier releases the withheld depreciation.
Condition matters here, which is why a dated inspection from before the storm is worth having. It answers the depreciation argument with a record instead of a memory.
If the claim is denied or the offer is low
A denial does not end the roof claim process. It is a written position, and it has to state its reasoning. Read it closely. Common reasons are pre-existing damage, wear treated as maintenance, or a finding that the cause falls outside the policy. That reasoning tells you exactly what evidence an appeal needs.
Answer it with something new. A line item estimate from a licensed contractor, additional photographs, or a fresh report from an accredited inspector that addresses the stated reason head on. Send the appeal in writing and keep a copy.
If the appeal stalls, you have further options: your state department of insurance accepts consumer complaints and can mediate, a public adjuster works for you rather than the carrier, and an attorney who handles property damage claims can take over a complex file. Each costs something. Weigh that against the gap you are arguing about.
Choosing the contractor who does the work
Confirm the license and the insurance, and ask for the certificates rather than a verbal yes. Get written, itemized estimates from three local companies so you can compare scope as well as price. Be cautious with anyone who knocks on the door after a storm, pushes for a signature that day, or offers to absorb your deductible.
Get an independent read on the damage
Documentation decides most claims, and it is the part of the roof claim process you control. Find an accredited NRCIA inspector near you in the member directory and get the roof recorded before the adjuster arrives.
LeakFREE®, Forensic ROOF®, Mr. RoofCheck®, InspectionPLUS®, Today’s Inspection… Tomorrow’s Protection®, and Got Leaks?® are registered trademarks of Field Gate FLP, used by permission. RoofGUARD™, ForensicGUARD™, DisasterGUARD™, E3GUARD™, and Think Like a Raindrop™ are trademarks of Field Gate FLP.